Hedge Funds 101
Hedge funds have to tell the SEC what they own. This guide covers how they do it, which funds HedgeFollow follows, and what the filings can and can't tell you. It assumes you know the basics of investing, such as what a stock and a short sale are.
Which funds count as hedge funds
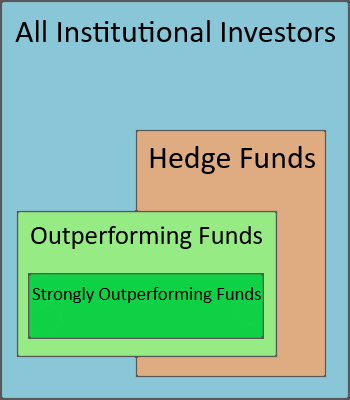
Legally, a hedge fund is a private fund open only to wealthy investors. HedgeFollow uses the term more loosely. We care less about how a fund is set up than about whether its stock picks are worth following, and we track every institution that files a 13F. For any count or total, you can choose which group of funds it covers:
Hedge funds
Hedge funds in the broad sense: famous ones like Bill Ackman's Pershing Square and Michael Burry's Scion, along with private equity firms, venture capital firms and other private funds that file 13Fs, and famous investors such as Warren Buffett's Berkshire Hathaway, which is not technically a hedge fund. Large banks, market makers and the like are left out.
Popular hedge funds
The best-known funds, run by famous investors such as Warren Buffett, David Tepper and Bill Ackman.
All institutional investors
Every 13F filer: the hedge funds above, plus banks such as JPMorgan Chase and Morgan Stanley, pension funds, insurers, mutual fund companies and market makers. Many of these hold thousands of stocks, often for clients or for very short periods, which makes their picks harder to read, but some investors like to follow how the giants rebalance each quarter.
Outperforming funds
Funds with a HedgeFollow rating of 3 stars or more: those whose top holdings beat 60% of rated funds over three years (see how we rank hedge funds). These can be any kind of institution, not only hedge funds.
Strongly outperforming funds
Funds rated 4 stars or more, the top 20% of rated funds. They are a subset of outperforming funds.
Grouping funds this way answers questions like: which stocks are the strongest funds buying? Which are they selling? The groups overlap, as the diagram shows.
The filings that show what funds own
Funds report their holdings to the SEC in two ways: a full list every quarter, and quicker filings when they take or change a large stake.
13F: every quarter
Every institutional investor with $100 million or more in US stocks and other "13F securities" files a 13F each quarter, listing its holdings on the quarter's last day. It's due within 45 days. The next deadline is Monday, November 16, 2026, for holdings as of September 30, 2026. Most funds file in the last week or two before a deadline.
Most of HedgeFollow's charts and lists of quarterly activity come from 13Fs: what each fund bought and sold, compared with the quarter before.
Reporting dates
A 13F reports holdings as of the end of the quarter, so many records on HedgeFollow share that date (2026-06-30, for example), however much later they were filed.
13D and 13G: stakes over 5%
When a fund comes to own more than 5% of a company, it has to say so much sooner, on a Schedule 13D or 13G, and again when the stake changes. These filings can arrive any business day, so they show a fund's moves as they happen. What separates the two is what the fund means to do with its stake.
Passive stakes: the 13G
A fund that simply thinks the stock is a good investment, and has no plan to influence the company, can file the shorter Schedule 13G. Institutions file it within 45 days after the end of the quarter in which they passed 5%; other passive investors within 5 business days.
Activist stakes: the 13D
A fund that means to push the company to change, by seeking board seats, a sale, a break-up or new management, must file a Schedule 13D within 5 business days, saying what it plans, and update it within 2 business days of any material change.
That's where activist funds differ from most investors, who buy a stock and hope management does well. Years ago, David Einhorn's Greenlight Capital bought a large stake in General Motors and pushed it to split its stock into a dividend-paying share and a growth share. Shareholders sided with GM, but the fight put the company in the spotlight, and many read the vote as confidence in its management.
Form 4: funds as insiders
Company insiders, meaning officers, directors and owners of more than 10% of a company's stock, report their trades on Form 4 within 2 business days. A fund that owns over 10% of a company, or has someone on its board, files Form 4s too, so these show its trades in that stock almost as they happen. See Insider Trading 101 for more.
Following the latest filings
The Hedge Fund Tracker shows every one of these filings as it comes in. Follow the stocks and funds you care about to see their filings together in My Tracker, and get alerts when they trade.
What the filings can't tell you
Following funds through their filings has real limits, and it's worth knowing them before acting on what you see.
The delay
A 13F is about six weeks old when it's filed on the deadline, and about four and a half months old when the next one replaces it. A fund may have sold a stock long before anyone sees that it owned it.
That matters less than it sounds. Many funds hold stocks for years and build positions over several quarters, which you can see as a staircase in the Ownership column on a fund's page. Rated funds show which ones have done well with their long-term holdings. And 13D, 13G and Form 4 filings come within days.
Only 13F securities
A 13F covers only 13F securities, which are mainly stocks, ETFs and options traded in the US. Foreign stocks that trade only abroad, most bonds, cash and private investments are left out, so for a fund that invests mostly outside the US the picture is incomplete.
For most funds that follow stocks, it covers what matters. Thousands of US stocks are 13F securities, along with hundreds of large foreign companies listed in the US, such as Alibaba and Toyota, and ETFs that hold foreign markets.
Only long positions
Funds report what they own, not what they've sold short. A stock in a 13F may be one side of a hedge, bought against a short you can't see, so its presence doesn't always mean the fund expects it to rise.
Many funds don't short at all, and their holdings are bets on the stock. Funds that hedge with put options have to report them, so those hedges are visible.
What HedgeFollow adds
Every filer, every filing
Some sites track only a few famous funds, which gives a skewed picture. HedgeFollow tracks every 13F filer and every 13D, 13G and Form 4, so you can see what institutions as a whole are doing, or narrow it to the groups above.
Up to date
Quarterly and non-quarterly filings are hard to combine, so many sites use only 13Fs. HedgeFollow merges them all: a fund's page shows its latest known portfolio, built from every filing it has made.
Cleaned data
Fund filings are full of mistakes: wrong units, misreported share counts, duplicated or misidentified holdings. Most go unnoticed in the SEC's database. HedgeFollow has corrected more than a million of them. We also keep different kinds of securities apart, such as options, warrants, notes and units, so they aren't added up as if they were the same thing.